

TLDR
- SK Hynix (SKHY) opened Thursday at $189 after falling 3% the outdated session.
- Wolfe Compare raised its SKHY tag target to $250 from $200, implying roughly 32% upside.
- Analyst Chris Caso reiterated a Purchase ranking, citing sturdy memory pricing and money waft.
- Wolfe also lifted its Micron (MU) target to $1,500 sooner than earnings on September 30.
- Wall Boulevard holds a Precise Purchase consensus on every memory chipmakers.
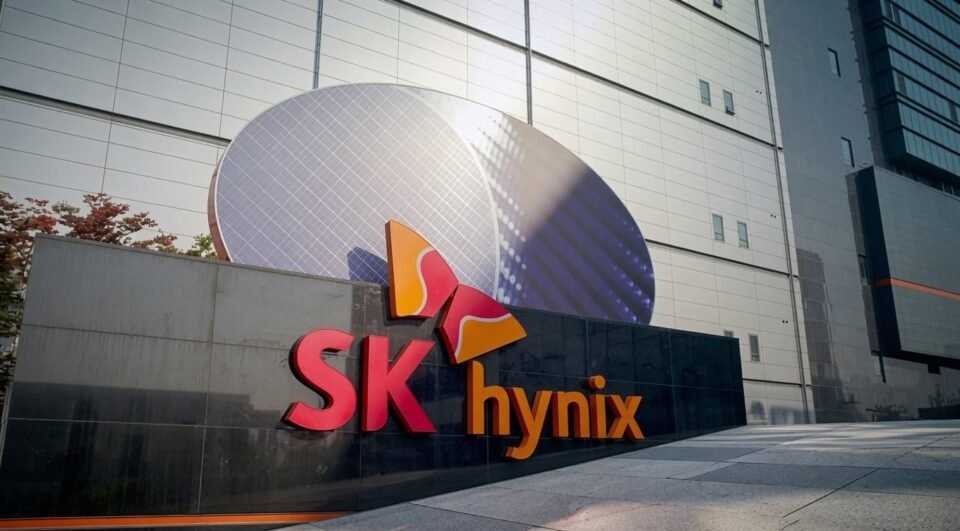
SK Hynix (SKHY) inventory opened Thursday at $189 after shedding 3% the day sooner than. The inventory honest not too lengthy in the past touched a yearly excessive of $199.86 nonetheless has yet to sure the $200 label.

Wolfe Compare thinks that ceiling won’t preserve for lengthy. Analyst Chris Caso raised his tag target on SKHY to $250 from $200, implying about 32% upside from modern levels.
Caso ranks 82nd out of more than 12,500 analysts tracked by TipRanks. His calls like a 63% success price and an moderate return of 32.70%.
The upgrade wasn’t cramped to SK Hynix. Wolfe also reiterated a Purchase ranking on Micron (MU), surroundings a $1,500 tag target on that inventory too.
Why Wolfe Is Bullish on Memory
Caso pointed to endured pricing strength across the memory sector because the main driver in the again of the elevated targets. He expects demand to outpace supply thru not lower than 2028.
High-bandwidth memory pricing and sooner means expansion are also part of the thesis. Caso expects additional HBM tag will improve in 2027, layered on top of the rally that began in gradual 2025.

He addressed concerns about “de-speccing” in memory chips too. In response to Caso, lowered specs stem from cramped supply reasonably than HBM shedding fee.
Prolonged-time-frame agreements cap costs on part of the bit shipments every firms promote. But Caso sees advance-time-frame upside coming from change exterior those contracts.
Cash Waft and Buybacks in Focal level
The analyst highlighted free money waft as a key part of the legend. He expects SK Hynix and Micron to generate ample profit 2026 and 2027 to repurchase 32% and 25% of their respective market caps.
That would perchance perchance improve 2027 earnings per portion by as much as 47% for SK Hynix and 34% for Micron, in step with Wolfe’s estimates. If sturdy stipulations raise into 2028, blended buybacks would perchance perchance top 50% of every firms’ market fee.
“While mighty of the distinct outlook is already identified, we deem the money waft would perchance be complicated to fail to have in mind,” Caso wrote in a blow their personal horns to merchants.
Caso also factored in forex effects. A 14% strengthening of the Korean won in opposition to the greenback at some level of the quarter would perchance perchance weigh on SK Hynix’s working margin, he eminent.
Micron reviews fiscal fourth-quarter earnings on September 30. Wall Boulevard expects EPS of $31.49, up sharply from $3.03 a twelve months earlier, with income projected to soar spherical 350% to $50.91 billion.
Wall Boulevard maintains a Precise Purchase consensus on every shares. TipRanks records reveals the moderate tag target implies elevated upside for Micron than for SK Hynix.
Year-to-date, Micron inventory has climbed about 276%. SK Hynix’s U.S.-listed shares are up spherical 13% over the same stretch.

Ken Carey is a markets reporter covering cryptocurrency, Bitcoin, Ethereum, exchanges, law and on-chain records. He has traded crypto and futures markets for 6 years and makes a speciality of what tag strikes, ETF flows and protection adjustments mean for merchants. Adjust to on X @WallStAlphaPro
