Knowing by Simon Schneider, CEO of Sygnum Europe
When the Markets in Crypto Assets Law (MiCA) came into drive, it did something that had eluded the digital asset sector in Europe for years: it created a single, coherent rulebook.
For the first time, a crypto asset provider provider (CASP) authorized in one Member Instruct can passport its companies and products trusty via the European Union and European Economic Assign, and customers trusty via the bloc can resolve amongst a increasing self-discipline of licensed, supervised suppliers. That is an actual fulfillment, and one the alternate must collected not snatch as a right.
As the session on MiCA’s overview closes, the level of interest must collected now be on calibration: holding what works, and being moral about where the compliance burden has grown faster than the hazards it is meant to handle.
The associated price of a unified market
Delivery up with what MiCA got lovely. Sooner than it, a agency attempting to feature trusty via Europe faced a patchwork of nationwide regimes, divergent registration requirements, and, in some markets, no bespoke regime at all.
A unified market changes the economics of organising a serious alternate. It lets suppliers invest in one authorization and one compliance architecture in space of 30, and it supplies customers something they truly non-public the profit of: replace amongst extra than one suppliers competing on quality, set apart, provider and security, all held to a total typical.
Linked: MiCA is coming for DeFi vaults, but legislation will be not easy
Passporting is the mechanism that turns 30 fragmented markets into one addressable market of roughly 450 million of us, and it is the single strongest cause of a globally cell alternate to produce in Europe in space of in other locations.
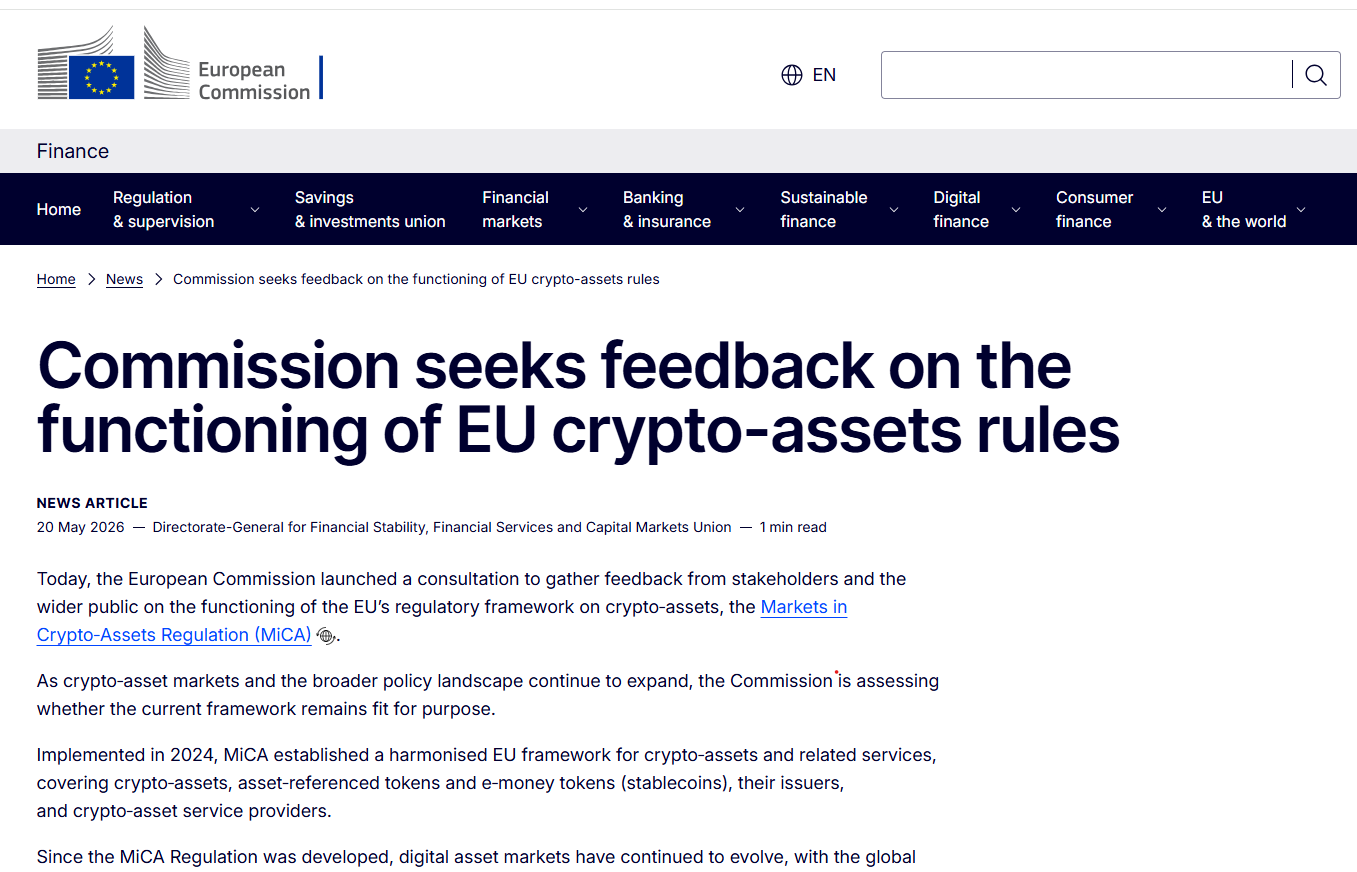
Consultation on MiCA’s overview closes Sept. 30. Supply: European Commission
MiCA has raised the barrier to entry by imposing a extra anxious authorization and compliance framework. In return, on the opposite hand, an authorized CASP gains ranking admission to not merely to a single Member Instruct, but to the entire EU single market.
The related query for the overview is subsequently whether the tasks for market ranking admission to live proportionate to the scale of the market they free up.
Adjust the likelihood, not the explain
The precept that must collected files the overview is easy: legislation must collected observe where there are precise risks to market members or to market balance, and it wants to be proportionate to those risks.
The assign a provider touches client cash, custody of assets, market integrity, or monetary balance, sturdy principles are usually not factual acceptable but major. That is where supervisory attention belongs, and that’s where the alternate has the least to complain about.
Compliance frameworks must collected in the extinguish be judged by one typical: fabricate they meaningfully reduce back possibility?
Over time, frameworks are inclined to acquire principles, reporting requirements and documentation tasks, steadily adding complexity and payment and not utilizing a corresponding possibility-reduction profit.
Linked: MiCA level of interest shifts from rulemaking to supervision, ESMA chair says
A overview must collected subsequently articulate every requirement and protect most efficient of us that handle a clear and self-discipline cloth possibility. Principles that go that take a look at must collected protect. Principles that fabricate not wants to be simplified, streamlined, or removed. Proportionality is just not a loophole; it is the self-discipline that keeps a rulebook credible.
Be moral in regards to the payment curve
It wants to be acknowledged openly that compliance prices for CASPs non-public risen vastly below MiCA. That is just not, by itself, a criticism. Some of that payment is the associated price of admission to a nicely-organized and treasured market, and a nicely-go agency wants to be ready to pay it. Nonetheless payment is just not a neutral truth for the market as an entire.
Compliance overhead falls hardest on smaller corporations and more fresh entrants, the very members who drive competition and innovation. When the fastened payment of being authorized climbs high ample, it stops being a safeguard and begins being a barrier to entry, entrenching incumbents and scaling down the replace that the single market turned into as soon as speculated to develop better.
The possibility to tag, subsequently, is never any single rule but the cumulative route of shuttle. If the overview adds materially to the regulatory burden and not utilizing a clear possibility-essentially based justification, the likely consequence is just not a safer market but a smaller one: much less innovation and fewer corporations engaging to produce in Europe.
Linked: Greece gets first MiCA entrants as watchdog denies Binance-Lagarde declare
Digital asset companies are surprisingly cell, and a few might possibly presumably possibly also merely gradually direct unique investment toward jurisdictions that offer similar market ranking admission to at lower friction. If that occurs, European customers discontinue up with much less replace, and European supervisors oversee a smaller fragment of a world explain that continues regardless.
What a factual overview appears to be like admire
None of this argues for deregulation. It argues for a overview constructed round proportionality: exhaust this likelihood to seem for laborious on the necessities that generate payment and not utilizing a matching profit, to present corporations room to innovate and produce, and to ask, at every turn, whether a given obligation is preserving the market or merely taxing it. A couple of examples illustrate the level:
- Tiered legislation by size and possibility: A diminutive startup with a handful of customers must collected not face the the same compliance burden and prudential requirements as a multinational company managing billions in assets. Introducing proportionate tiers in line with asset volume, client corrupt or systemic relevance would lower boundaries to entry for emerging avid gamers while placing forward sturdy oversight where it matters most.
- Twin licensing for e-cash tokens: Custody and transfer of EMTs can trigger further legislation, honest like Payment Provider Directive (PSD2), on top of MiCA licensing. This overlap creates duplicative compliance prices and trusty uncertainty and not utilizing a clear user protection profit. A clearer delineation — or a single-license pathway — would reduce back friction while maintaining supervisory coverage.
Payment Providers Directive. Supply: ECB
- Rigid reserve requirements for stablecoins: Issuers must deal with not much less than 30% of reserves as monetary institution deposits. In a rising-payment ambiance, this limits yield opportunities; in a banking crisis, it concentrates counterparty possibility. A extra versatile allocation framework — one that lets in high-quality liquid assets previous monetary institution deposits — might possibly presumably possibly also enhance resilience without compromising redemption ability.
Europe has constructed something uncommon: a nicely-organized, unified, credibly regulated market for crypto assets. The prize now might possibly presumably possibly be to protect up it lovely to the corporations that develop it work.
Getting the balance lovely is in each person’s passion, regulators and alternate alike, and the impending months are the time to ranking it lovely.
About the author: Simon Schneider is CEO of Sygnum Europe, the European arm of digital asset banking neighborhood Sygnum. He leads Sygnum’s European operations as the firm expands trusty via the EU below the Markets in Crypto-Assets Law (MiCA).
Linked: Is there any likelihood left to keep the CLARITY Act?
