

TLDR
- McDonald’s unveiled its NEXT growth device at Investor Day, in conjunction with restaurant redesigns and AI-powered programs.
- The firm plans roughly $8.5 billion in franchisee make stronger through 2036, starting with $5 billion by 2030.
- MCD stock fell 5% on the news and touched a attain four-365 days low of $234.03.
- U.S. connected sales grew to grow to be negative in July and August, with Q3 expected to enact a microscopic negative.
- Analysts widely nick tag targets nonetheless many kept obvious rankings, making a guess on long-term payoff.
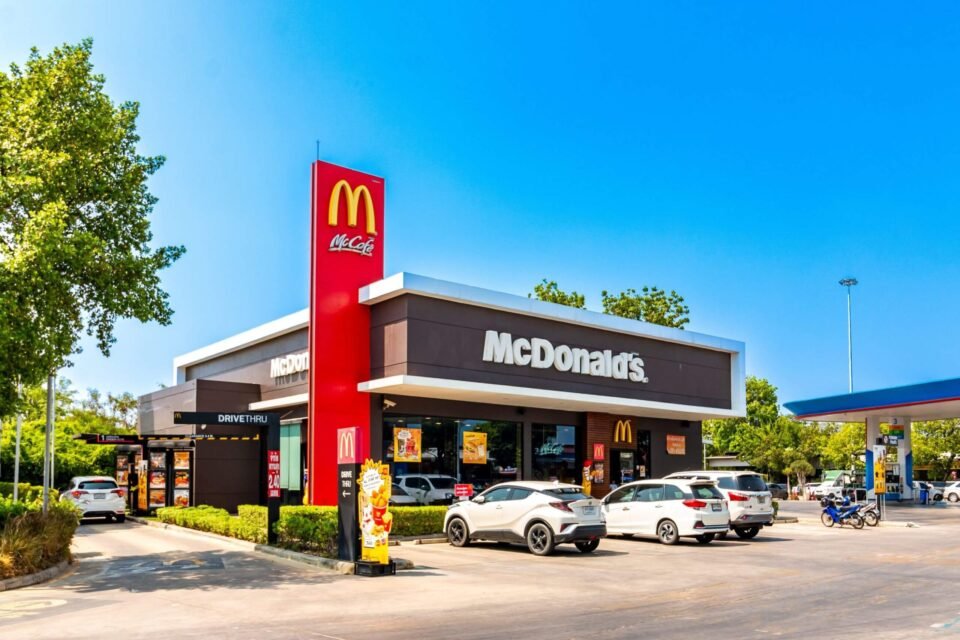
McDonald’s stock sits attain a four-365 days low after consumers reacted sharply to the firm’s most unusual growth opinion. Shares fell merely about 5% final Wednesday and dropped as noteworthy as 6.5% all over the session earlier than settling. The stock kept sliding Thursday and Friday, and it’s now down roughly 23% for the 365 days.

The selloff adopted McDonald’s Investor Day, where administration laid out its NEXT device. The opinion covers restaurant redesigns, menu upgrades, centered advertising and marketing, and AI-powered ordering and inventory programs.
It’s an ambitious pitch. But Wall Avenue’s most most critical bother isn’t the vision itself, it’s the tag label and the timeline.
What’s Driving the Sell-Off
McDonald’s plans to employ about $8.5 billion supporting franchisees through 2036. Roughly $5 billion of that lands earlier than 2030, covering rent reduction and $1.5 billion to $2 billion in capital make stronger.
Administration says the investments could well perhaps perchance also tranquil clutch restaurant-diploma effectivity by 2.5 percentage device. That works out to about $100,000 in extra annual money drift per average U.S. location.
The bigger device: an adjusted working margin in the low-to-mid-50% vary by 2030. That’s up from 47% in the foremost half of 2026. Getting there requires precise money up entrance, and that’s rattling consumers watching attain-term numbers.

Bernstein’s Danilo Gargiulo called the spending burden the “greatest surprise” of the event. He estimates plump implementation could well perhaps perchance also price roughly $800,000 per average U.S. restaurant, stacked on top of long-established reworking funds.
Bank of America pegs the specified sales clutch at 7% to 8% per restaurant to justify the funding, assuming a 70/30 funding split between franchisees and the firm. That’s a colossal expose given recent prerequisites.
Sales Are Already Aloof
Site visitors traits aren’t helping the memoir. McDonald’s acknowledged U.S. connected sales were negative in July and August, with the third quarter likely finishing a microscopic negative no matter some enchancment in September.
2nd-quarter worldwide connected sales rose perfect 1.3% 365 days over 365 days. That’s down from 3.8% in the foremost quarter and 3.1% for all of 2025. U.S. customer counts undoubtedly grew to grow to be negative.
Raymond James analyst Brian Vaccaro acknowledged NEXT’s success will likely be measured “in years in preference to quarters.” McDonald’s hasn’t given rollout timelines for several pieces of the opinion, which leaves consumers guessing on pacing.
Vaccaro additionally flagged a tag jam. Many like a flash-food meals now bolt $10 to $13, inserting McDonald’s in assert competition with informal-eating and like a flash-informal price provides.
Plenty of companies trimmed tag targets after the event. Baird nick to $250 and kept a Neutral ranking. BTIG diminished to $295 whereas keeping a Aquire. RBC dropped to $285 with a Sector Gather ranking. JPMorgan nick to $260 nonetheless kept an Overweight ranking.
Now not every analyst grew to grow to be cautious even supposing. UBS reiterated its Aquire ranking and $320 device, pointing to the NEXT device’s focal point on same-store sales and customer counts.
J.P. Morgan’s John Ivankoe acknowledged McDonald’s records infrastructure could well perhaps perchance also give it an edge over smaller opponents. Deutsche Bank’s Lauren Silberman acknowledged she’s grown extra confident that AI instruments can enhance restaurant profitability over time.
BMO’s Andrew Strelzik called the margin targets achievable and stayed bullish on valuation. He tranquil expects diminutive attain-term upside unless the investments portray up in growth numbers.
Bigger than half of analysts tracked by FactSet tranquil rate MCD a Aquire. Their average device sits 27% above recent levels.
Bernstein kept its Market Gather ranking and $295 tag device, noting the beverage open hasn’t lifted sales sufficient to offset broader stress. The firm additionally acknowledged the unusual chicken platform open is extra out than expected.

Ken Carey is a markets reporter covering cryptocurrency, Bitcoin, Ethereum, exchanges, guidelines and on-chain records. He has traded crypto and futures markets for six years and specializes in what tag moves, ETF flows and policy changes imply for consumers. Apply on X @WallStAlphaPro
