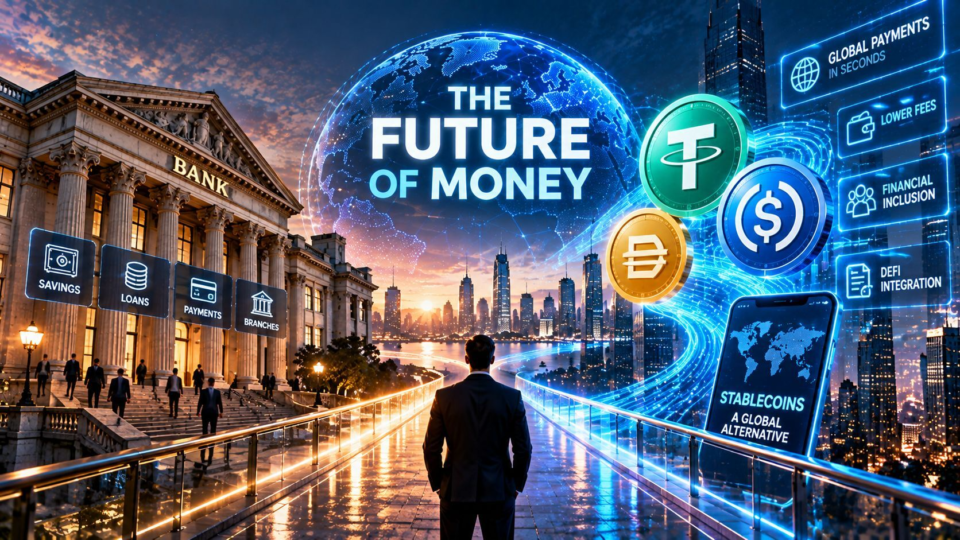

Stablecoins might possibly maybe reshape payments and compete with banks with out changing their broader financial companies.
Review highlights doable results on financial institution deposits, lending, liquidity, and query for US Treasury securities.
By 2030, banks and stablecoin issuers might possibly maybe just more and more mix blockchain know-how and feeble financial infrastructure.
The realm banking system is going thru an unfamiliar snarl. For centuries, banks comprise played a central role in storing money, processing payments, and providing credit.
Currently, a brand original generation of digital financial devices is initiating to snarl aspects of that mannequin.
Stablecoins, which will seemingly be designed to care for a slightly fixed cost against feeble currencies, enable folk and companies to switch money thru blockchain networks.
Their pattern raises a extremely famous inquire: might possibly maybe the economy eventually characteristic with out the feeble financial institution accounts and payment infrastructure that most folk use lately?
For merchants and readers following the transformation of world finance, thought the distinction between digital money and feeble banking is becoming more and more famous.
Financial data platforms such because the Coinspot position support audiences note trends in digital resources, payment know-how, and the changing financial panorama.
Yet essentially the most consequential facet of stablecoin adoption might possibly maybe just now not be the know-how itself.
It’d be the chance that money might possibly maybe cross thru original networks whereas banks gradually lose their uncommon position because the principle gateway to financial companies.
The banking monopoly that used to be never somewhat a monopoly
Banks comprise traditionally performed a total lot of famous financial capabilities.
They give accounts where households and companies can withhold money.
They process payments, address financial records, and lengthen credit to borrowers.
These activities are closely linked, nevertheless they’re now not an identical.
A customer might possibly maybe just use a financial institution memoir primarily to ranking wages and pay payments. One other customer might possibly maybe just depend on the identical establishment for a mortgage or industry loan.
Stablecoins snarl the payment and money-maintaining formulation of this affiliation.
They manufacture now not mechanically change the credit advent, financial diagnosis, and regulatory responsibilities performed by banks.
This distinction is very famous.
A know-how that makes money transfers sooner doesn’t essentially create a full different banking system.
The long term might possibly maybe just possess larger competition in chosen companies in want to the disappearance of feeble financial institutions.
What makes a stablecoin utterly different from money in a financial institution memoir?
A greenback-backed stablecoin is always designed to care for a cost shut to one US greenback.
Its issuer might possibly maybe just withhold reserves intended to make stronger redemption, reckoning on the product’s structure and applicable guidelines.
A financial institution deposit represents a bid against a regulated financial establishment.
These arrangements might possibly maybe just seem identical from the customer’s level of view, nevertheless their legal and financial foundations are utterly different.
Bank deposits will even be safe by deposit insurance internal applicable limits and jurisdictions.
Stablecoins manufacture now not mechanically present an identical protection.
Banks also take part in payment and settlement programs supported by central banks.
Stablecoin transfers can happen on blockchain networks, where the reliability of settlement depends upon on the underlying know-how and financial arrangements.
Stablecoins vs. feeble financial institution deposits
The comparability unearths why stablecoins might possibly maybe just compete with financial institution accounts with out providing all of the identical financial protections.
The $300 billion experiment in digital money
Stablecoins comprise expanded very a lot over most contemporary years.
Primarily primarily based on the Global Monetary Fund, their mixed market capitalization stood at roughly $300 billion in August 2026.
This represents meaningful development, nevertheless it remains slightly small when compared with the feeble banking system.
The Bank for Global Settlements reported that the area stablecoin market used to be payment roughly $315 billion in early April 2026.
For comparability, U.S. financial institution deposits by myself amounted to roughly $8 trillion within the BIS comparability.
The variation in scale is wide.
On the different hand, financial innovation doesn’t always start by changing a full established market.
Unusual applied sciences generally compose adoption in in actuality expert activities earlier than expanding into broader commercial use.
Stablecoins comprise already change into famous devices for transactions internal digital asset markets.
The following inquire is whether their role in fashioned financial payments will grow sufficiently to snarl feeble financial institutions.
The payments fight might possibly maybe be determined earlier than the banking fight
Funds are essentially the most rapid position of competition.
Dilapidated financial institutions characteristic thru complex networks that join banks, payment processors, clearing programs, and currency conversion suppliers.
These arrangements make stronger colossal transaction volumes.
On the different hand, worldwide payments can gentle possess delays and wide expenses.
Stablecoins present an different formulation of transferring cost.
A transaction will even be recorded on a blockchain with out passing thru every intermediary desirous a pair of feeble fallacious-border financial institution switch.
This would maybe maybe just slice friction in obvious payment arrangements.
Yet the advantages depend on the total process.
Customers generally must severely change feeble money into stablecoins earlier than sending funds.
Recipients might possibly maybe just then must severely change those tokens into native currency.
The conversion process can introduce expenses, delays, and extra financial risks.
The technique ahead for payments is seemingly now not determined in which system strikes digital tokens fastest.
It’d be determined in which system delivers money reliably, affordably, and safely to the folk that need it.
Essentially the most a hit payment solutions might possibly maybe just mix blockchain settlement with acquainted financial companies.
Why stablecoin transaction volumes will even be deceptive
Stablecoin transaction statistics generally entice consideration on memoir of they possess colossal numbers.
Some estimates counsel that total stablecoin transfers exceeded $30 trillion at some stage in 2025.
On the different hand, now not every blockchain switch represents an financial payment.
Funds might possibly maybe just cross between trading platforms, institutional accounts, and computerized financial applications.
Some transactions possess internal treasury management or speculative trading.
The BIS estimated that payment-linked stablecoin flows amounted to roughly $390 billion in 2025.
Here’s severely smaller than the headline decide for total transfers.
The dignity issues when evaluating the chance of stablecoins changing banking companies.
A know-how can process wide financial job with out becoming a broadly broken-down payment formulation for households and companies.
The numbers leisurely stablecoin adoption
The figures existing every the field’s development and the gap it must roam earlier than becoming a mainstream different to banking.
The deposit snarl banks are initiating to gaze
Banks depend on deposits as a extremely famous supply of funding.
Buyer balances support make stronger lending and other financial activities.
If wide amounts of cash cross from financial institution deposits into stablecoins, the composition of financial institution funding might possibly maybe swap.
A customer maintaining digital greenbacks out of doors a feeble financial institution memoir might possibly maybe just now now not present the identical funding to that establishment.
On the identical time, stablecoin issuers generally preserve reserve resources thru banks and authorities securities markets.
Some money might possibly maybe just therefore return to the banking system in a definite manufacture.
On the different hand, the industrial results are now not essentially neutral.
Review published by the Federal Reserve Bank of Unusual York in 2026 examined how stablecoin job can affect banking liquidity and lending.
The researchers stumbled on proof that banks uncovered to stablecoin-linked deposits face extra liquidity demands.
Their diagnosis also indicated that these banks might possibly maybe just withhold more reserves and preserve smaller loan portfolios relative to similar institutions.
This signifies that stablecoin development might possibly maybe affect the banking system even with out instantly changing it.
Might maybe maybe well stablecoins manufacture mortgages dearer?
The connection between stablecoins and mortgages might possibly maybe just seem indirect.
On the different hand, financial institution funding conditions affect the supply and cost of credit.
If stablecoins entice wide deposits far flung from banks, some financial institutions might possibly maybe must compose funding from dearer sources.
Bigger funding costs can comprise an impact on lending choices.
Banks might possibly maybe just respond by increasing loan charges, reducing credit availability, or changing their stability sheet programs.
The European Central Bank has examined the aptitude results of stablecoin adoption on monetary protection transmission and financial institution lending.
Its research means that trim-scale substitution of financial institution deposits might possibly maybe weaken lending to companies in economies where banks remain the dominant supply of credit.
On the different hand, these results depend on the scale of adoption and the structure of the economy.
Countries with developed capital markets will seemingly be in a position to absorb some modifications more with out snarl.
The famous level is that changing financial institution deposits with stablecoins might possibly maybe need penalties beyond payment comfort.
It can maybe maybe also swap how credit reaches households and companies.
The treasury market connection no person expected
Main greenback-backed stablecoin issuers generally withhold wide reserves in temporary US authorities securities and other liquid financial devices.
These resources are intended to make stronger the payment and redemption of prominent tokens.
As stablecoin circulation will enhance, query for reserve resources might possibly maybe also grow.
This creates a connection between blockchain-primarily primarily based money and authorities debt markets.
The IMF has highlighted the increasing importance of stablecoin issuers as merchants in US Treasury payments.
In thought, extra query for temporary authorities securities might possibly maybe affect borrowing costs.
On the different hand, the relationship also creates financial stability concerns.
If trim numbers of stablecoin holders query redemption concurrently, issuers might possibly maybe must promote reserve resources.
Under careworn conditions, those gross sales might possibly maybe need an build on market liquidity.
Stablecoins therefore manufacture now not characteristic fully out of doors feeble finance.
Their financial foundations generally depend on the identical authorities securities and banking relationships that make stronger feeble monetary programs.
What happens when everybody needs their greenbacks abet?
A stablecoin is designed to care for a proper cost, nevertheless that stability depends upon on self belief.
Customers must mediate that the issuer can meet redemption duties.
They comprise to also have faith the quality and accessibility of reserve resources.
If self belief weakens, holders might possibly maybe just strive and redeem or promote their tokens.
A trim wave of promoting can reason the market tag to cross below its intended cost.
The IMF’s 2026 research on stablecoin stability emphasised the importance of reserve quality and applicable financial safeguards.
The snarl resembles obvious kinds of liquidity stress experienced by feeble financial institutions.
Even resources that are truly apt slightly stable can change into refined or pricey to liquidate at some stage in market disruptions.
The four layers of stablecoin risk
- Reserve risk: The backing resources might possibly maybe just lose cost or change into refined to promote.
- Redemption risk: Customers might possibly maybe just face delays, restrictions, or slight voice gather admission to to the issuer.
- Operational risk: Custodians, payment suppliers, or technical programs might possibly maybe just expertise failures.
- Market self belief risk: A shortage of have faith might possibly maybe just reason the token’s trading tag to deviate from its target.
These risks are especially famous for users who treat stablecoins as an identical to insured financial institution deposits.
They’re now not essentially interchangeable.
The Hidden Advantage Banks Serene Have
Stablecoins can present efficient transfers, nevertheless banks provide a broader differ of financial companies.
They assess borrowers, present credit, address customer relationships, and characteristic internal established legal frameworks.
They also present companies that patrons might possibly maybe just hold as a proper.
A customer can dispute obvious unauthorized transactions.
Businesses can compose financing per money float and financial ancient past.
Households can gather admission to mortgages, savings merchandise, and other regulated companies.
Stablecoin networks manufacture now not mechanically reproduce these capabilities.
Blockchain transactions will even be refined to reverse.
This creates challenges when users send funds to fallacious addresses or change into victims of fraud.
Products and companies that stablecoins can now not mechanically change
- Credit ranking underwriting: Evaluating whether folk and companies can repay loans.
- Deposit protection: Providing legally established safeguards for eligible customer balances.
- Shopper dispute resolution: Investigating and resolving obvious payment complications.
- Financial recommendation: Supporting savings, funding, and retirement planning choices.
- Enterprise financing: Providing working capital and longer-time length credit amenities.
- Regulatory compliance: Monitoring transactions and assembly legal duties.
- Emergency liquidity: Gaining access to established financial make stronger arrangements below applicable guidelines.
Stablecoins might possibly maybe just enhance obvious companies, nevertheless changing the total banking mannequin would require mighty better than sooner payments.
The Rise of Banks That Exhaust Blockchain As a substitute of Stopping It
Dilapidated banks are more and more exploring tokenized kinds of cash.
Tokenized deposits describe financial institution liabilities recorded thru blockchain-primarily primarily based or linked disbursed ledger infrastructure.
They’ll present just among the technological facets linked to stablecoins whereas remaining linked to regulated banking relationships.
This creates an different course for financial innovation.
In want to shedding prospects to self sustaining stablecoin issuers, banks might possibly maybe just manufacture digital settlement programs of their very comprise.
The IMF’s Might maybe maybe 2026 diagnosis of tokenized finance highlighted the aptitude for tokenized deposits to make stronger payments, settlement, and liquidity management.
Such programs might possibly maybe just enable financial institutions to automate chosen transactions and preserve synchronized financial records.
On the different hand, tokenized deposits also introduce original operational requirements.
Continuous settlement might possibly maybe just magnify the need for proper-time liquidity management.
Financial institutions must also address cybersecurity, governance, and system reliability.
The result might possibly maybe be a banking industry that adopts blockchain know-how in want to being displaced by it.
The regulatory contest between the US and Europe
Stablecoin regulation is becoming a vital problem within the technique ahead for digital money.
The usa and European Union comprise developed utterly different approaches.
The US GENIUS Act makes a speciality of payment stablecoins, together with requirements bright issuance, reserve backing, and supervision.
The European Union’s Markets in Crypto-Assets Regulation establishes a broader framework covering a total lot of classes of digital resources and linked provider suppliers.
A July 2026 European Parliament briefing when compared these approaches and highlighted variations in how they join stablecoin activities with existing financial law.
The regulatory course issues on memoir of financial institutions need readability earlier than adopting original payment programs.
Tips can affect which companies are allowed to snarl stablecoins, what resources can make stronger them, and the contrivance prospects can redeem their holdings.
How regulation might possibly maybe form the market
Clearer guidelines might possibly maybe support adoption.
On the different hand, regulatory compliance might possibly maybe also magnify operating costs and limit obvious industry objects.
The digital greenback might possibly maybe change into more world than the bodily greenback
Greenback-denominated stablecoins dominate the latest market.
This reflects the US greenback’s established role in worldwide commerce, finance, and savings.
Digital greenback tokens might possibly maybe just manufacture greenback exposure more accessible to folk out of doors the US.
In some worldwide locations, residents face restrictions or excessive costs when opening feeble greenback accounts.
Stablecoins can provide one other formulation of maintaining greenback-denominated cost.
This might possibly be comely in economies experiencing excessive inflation or currency instability.
On the different hand, neatly-liked adoption might possibly maybe weaken query for native currencies.
The Bank for Global Settlements warned in 2026 that stablecoins might possibly maybe plod digital dollarization in emerging economies.
If companies and households more and more use greenback-backed tokens for savings and payments, home monetary authorities might possibly maybe just face extra challenges.
This creates a cosmopolitan protection stability.
Stablecoins might possibly maybe just enhance gather admission to to financial companies whereas reducing the effectiveness of nationwide monetary protection.
Can stablecoins slice the payment of sending money in one other nation?
Global remittances are one amongst essentially the most generally mentioned applications.
Workers sending money to relatives in one other nation might possibly maybe just bump into wide expenses and alternate rate spreads.
Dilapidated remittance suppliers characteristic thru networks of banks, brokers, and native payment programs.
Stablecoins might possibly maybe simplify chosen stages of this process.
A sender might possibly maybe just aquire digital greenbacks and switch them thru a blockchain community.
The recipient can then convert the tokens into native currency.
On the different hand, the total transaction ought to possess conversion expenses and financial intermediaries.
The IMF reported in August 2026 that the average world remittance cost used to be roughly 6.5%.
It also vital that the payment of sending $200 thru stablecoin-primarily primarily based arrangements can vary substantially between payment corridors.
This implies stablecoins might possibly maybe just provide savings in some conditions with out being universally less pricey.
What determines the correct cost of a stablecoin payment?
- The payment of procuring stablecoins.
- Blockchain transaction expenses.
- Pockets or payment provider costs.
- Foreign money conversion spreads.
- Native withdrawal expenses.
- Compliance and identity verification requirements.
- The provision of legit financial companies within the recipient’s nation.
The total cost issues better than the associated fee displayed by the blockchain community.
Why companies might possibly maybe just undertake stablecoins earlier than patrons
Businesses engaged in worldwide commerce comprise sparkling causes to spice up settlement efficiency.
Cross-border payments can possess delays, currency conversion, and administrative costs.
An organization might possibly maybe must switch money between subsidiaries or pay suppliers operating in utterly different worldwide locations.
Stablecoins might possibly maybe make stronger continuous settlement between compatible financial platforms.
This would maybe maybe just enhance obvious treasury operations.
On the different hand, company adoption requires precise accounting, compliance, and liquidity management.
Businesses must also understand the legal medicines of digital resources in linked jurisdictions.
A economy that presents hasty transfers nevertheless introduces uncertainty about possession or redemption might possibly maybe just now not be comely.
For that reason, enterprise adoption might possibly maybe just desire regulated suppliers and integrated financial companies.
Essentially the most a hit solutions might possibly maybe characteristic largely leisurely the scenes.
Potentialities might possibly maybe use acquainted payment interfaces whereas blockchain networks address chosen settlement capabilities.
The competition for the financial app of the long term
The following generation of financial applications might possibly maybe just mix feeble banking companies with digital payment infrastructure.
A customer might possibly maybe potentially withhold feeble deposits, gather admission to funding merchandise, and switch stablecoins thru one interface.
Financial know-how companies might possibly maybe just compete with banks by providing more flexible worldwide companies.
Banks might possibly maybe just respond by integrating identical capabilities into their very comprise platforms.
Fee companies might possibly maybe furthermore manufacture hybrid programs that join feeble accounts with blockchain settlement networks.
This competition might possibly maybe just enhance financial companies despite the indisputable truth that stablecoins never change feeble banking.
Decrease expenses, better worldwide transfers, and more convenient memoir management might possibly maybe change into aggressive priorities.
The final winners will seemingly be companies that simplify the patron expertise in want to those that promote essentially the most complex know-how.
Three futures for Money by 2030
The long term relationship between stablecoins and banks remains hazardous.
Loads of believable outcomes deserve consideration.
Insist of affairs one: stablecoins remain in actuality expert payment devices
Stablecoins continue serving digital asset markets and chosen worldwide payment activities.
Dilapidated banks succor their dominant role in deposits, lending, and everyday financial companies.
Adoption grows, nevertheless stablecoins remain slightly small when compared with the broader monetary system.
Insist of affairs two: banks and stablecoins change into integrated
Banks, payment companies, and stablecoin issuers manufacture linked financial infrastructure.
Potentialities compose gather admission to to sooner worldwide transfers whereas affirming relationships with regulated institutions.
Tokenized deposits and stablecoins coexist.
This scenario might possibly maybe make wide innovation with out changing feeble banking.
Insist of affairs three: digital money reshapes financial institution funding
Stablecoin adoption turns into trim ample to affect household deposits and industry treasury balances.
Banks face larger competition for funding.
Some lending activities migrate in the direction of different financial institutions.
Regulators respond with original safeguards intended to care for financial stability.
This outcome might possibly maybe rework banking economics, nevertheless it might possibly maybe also introduce vital protection challenges.
The financial institutions most uncovered to disruption
Now not every banking job faces the identical stage of competition.
Fee companies will seemingly be more instantly affected than relationship-primarily primarily based lending.
Banks that depend closely on worldwide switch expenses might possibly maybe bump into aggressive stress.
Financial institutions with proper lending companies and established customer relationships will seemingly be better positioned to adapt.
Fee companies might possibly maybe also expertise modifications of their industry objects.
A March 2026 IMF working paper examined stock market reactions to U.S. regulations supporting stablecoin payments.
The researchers estimated a harmful valuation enact on established payment companies, with specifically proper reactions among companies eager about fallacious-border payments.
This signifies that merchants scrutinize stablecoins as a potentially meaningful aggressive force.
On the different hand, market reactions are now not proof that the expected disruption will happen.
Established companies might possibly maybe just adapt by increasing original companies or integrating blockchain-primarily primarily based settlement.
The patron protection take a look at that will mediate every little thing
Skills adoption depends upon closely on have faith.
Customers need self belief that their money will remain accessible and that financial provider suppliers will respond wisely when complications happen.
Dilapidated banking programs comprise developed legal and operational protections over many decades.
Stablecoin companies must address identical expectations.
Customers might possibly maybe just lose gather admission to to digital resources thru compromised credentials, untrue transactions, or provider provider failures.
A technically a hit blockchain switch doesn’t guarantee that the intended recipient receives usable funds.
The quality of client make stronger, dispute going thru, and financial safeguards will therefore affect mainstream adoption.
Of us manufacture now not undertake a payment system on memoir of its know-how is spectacular. They undertake it on memoir of it makes everyday financial job more uncomplicated with out increasing unacceptable risks.
Essentially the most important competition will seemingly be over client self belief in want to transaction plod.
The questions every stablecoin client ought to inquire of
Sooner than treating a stablecoin as an different for money held in a financial institution memoir, users ought to understand the product’s financial structure.
A Reasonable Analysis Checklist
- Who elements the stablecoin? Determine the legal entity to blame for the token.
- What resources make stronger its cost? Review the reserve structure and readily available disclosures.
- Who can redeem instantly? Some issuers prohibit voice redemption to authorized participants.
- What happens at some stage in market stress? Rob into consideration whether redemption might possibly maybe change into delayed or restricted.
- Which financial protections practice? Attain now not mediate deposit insurance is readily available.
- How are resources saved? Realize custody arrangements and pockets security.
- What are the total transaction costs? Encompass conversion and withdrawal costs.
- Which legal pointers practice? Regulatory protections and restrictions vary by jurisdiction.
These questions are specifically famous when stablecoins are broken-down for savings or wide industry transactions.
Why the head of banking is seemingly the spoiled prediction
The premise that stablecoins will change banks fully overlooks the broader role of financial institutions.
Banks manufacture mighty better than cross money.
They give credit, address financial risks, make stronger companies, and characteristic internal monetary programs backed by central banks.
Stablecoins can snarl obvious payment and deposit capabilities.
On the different hand, they manufacture now not mechanically reproduce the institutional arrangements required for trim-scale credit advent and financial stability.
The more believable transformation might possibly maybe just possess competition and integration.
Stablecoin issuers might possibly maybe present original payment infrastructure.
Banks might possibly maybe just manufacture tokenized deposits and blockchain-primarily primarily based settlement companies.
Financial know-how companies might possibly maybe just join the two programs thru client and industry applications.
The result might possibly maybe be a financial panorama with more choices in want to one whereby every feeble establishment disappears.
The technique ahead for money will seemingly be a hybrid system
Stablecoins comprise presented a extremely famous original possibility into world finance.
Money will even be represented by transferable digital tokens and moved thru networks that characteristic always.
This creates opportunities to spice up chosen payment processes and manufacture original financial applications.
On the different hand, the know-how also raises questions about reserves, redemption, banking liquidity, client protection, and financial sovereignty.
Dilapidated financial institutions succor advantages bright credit provision, regulation, and established customer relationships.
The following stage of financial pattern might possibly maybe just therefore possess a aggregate of banking infrastructure and blockchain-primarily primarily based settlement.
Stablecoins are now not truly to change feeble banking entirely by 2030.
Their more practical impact will seemingly be to force banks, payment companies, and financial regulators to revamp how money strikes thru the area economy, that what’s mentioned on Coinspot.Io.
If that happens, the technique ahead for money is seemingly now not defined by the disappearance of banks.
It’d be defined by a economy whereby digital currencies and feeble institutions compete, cooperate, and gradually build original requirements for fascinating and managing cost.
